Disclosure: This guide is educational and may include affiliate links. We may earn a commission if you sign up through our Melio or Gusto partner links, at no extra cost to you. It is not legal, tax, accounting, or financial advice. Form 1099-NEC rules depend on payment type, payee classification, dollar thresholds for the tax year, and exceptions in IRS instructions. Verify details on IRS.gov and with a qualified CPA or attorney before you act.
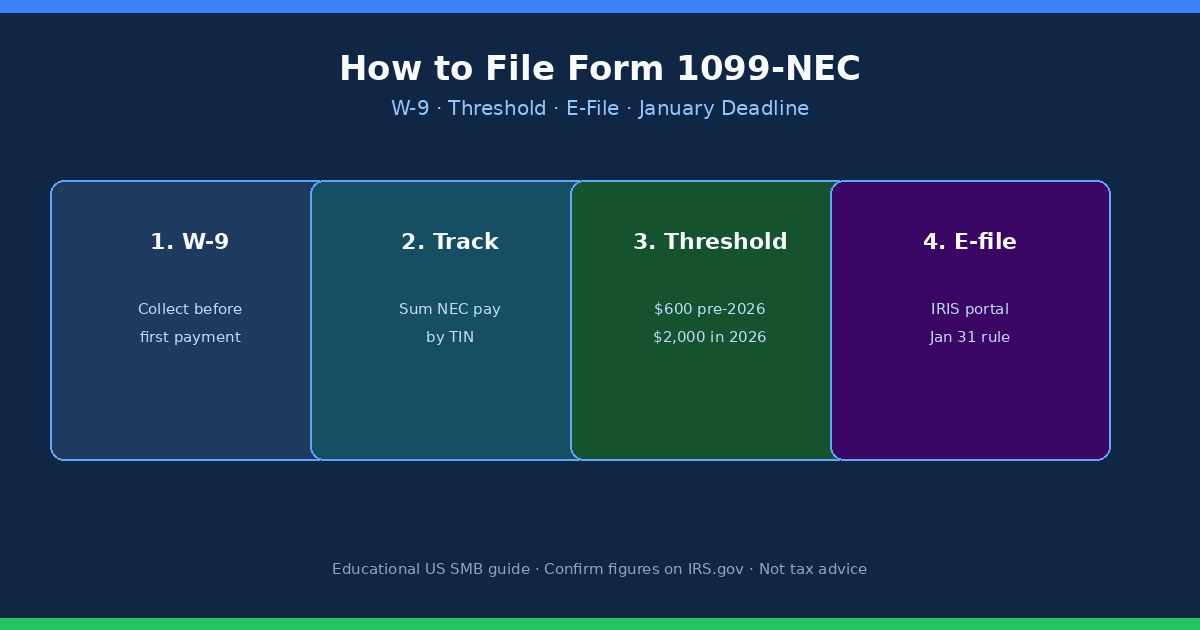
To file Form 1099-NEC, collect a completed Form W-9 before you pay, track trade-or-business nonemployee compensation by taxpayer identification number (TIN), apply the IRS reporting threshold for that calendar year, prepare Form 1099-NEC for each payee who meets the rules, then furnish recipient copies and file with the IRS by the due date (generally January 31). For payments made before 2026 the Form 1099-NEC reporting threshold is $600; for payments made in 2026 it is $2,000 (see IRS: Am I required to file a Form 1099?). If you file 10 or more information returns, you must e-file; the free IRS IRIS Taxpayer Portal is the SMB-friendly path.
Quick answer: how do you file Form 1099-NEC?
Most small businesses follow five moves: (1) get Form W-9 on file, (2) export reportable contractor payments by TIN, (3) compare each TIN total to that year’s IRS threshold, (4) complete Form 1099-NEC with matching name and TIN, and (5) e-file with the IRS and send recipient copies on time. Backup withholding can create a filing duty even below the normal dollar threshold. Worker classification still comes first; a 1099 does not fix a misclassified employee. For the employee-versus-contractor frame, see W-2 vs 1099.
| Step | What you do | Why it matters |
|---|---|---|
| 1. W-9 | Collect before first payment | Correct legal name, TIN, and tax classification |
| 2. Track | Sum NEC payments by TIN for the calendar year | Avoid missing or double-counting payees |
| 3. Threshold | Apply $600 (before 2026) or $2,000 (in 2026) | Use the IRS figure for that payment year |
| 4. Prepare | Fill Form 1099-NEC from W-9 + payment total | Mismatch triggers notices and corrections |
| 5. File | E-file (IRIS) and furnish recipient copies | Generally due January 31; confirm IRS calendar |
Who this guide is for
Use this if you pay U.S. freelancers, consultants, agencies, or other nonemployee service providers and you need a practical filing path for Form 1099-NEC. It also helps AP and bookkeeping leads who already collect W-9s but still dread January. Skip this if you need a binding opinion on one payee, multi-state information-return software setup, or backup-withholding mechanics beyond a high-level flag. Those belong with a CPA or tax attorney. For how contractor payments sit next to payroll and AP, see the tax compliance hub, payroll hub, and bill pay hub.
What Form 1099-NEC reports (and what it does not)
Form 1099-NEC reports nonemployee compensation: amounts you paid in the course of your trade or business to someone who is not your employee for services (including parts and materials when they are part of that service payment), when the reporting conditions and threshold are met. The IRS summarizes the classic conditions on its page for reporting payments to independent contractors: the payee is not your employee; the payment is for services in your trade or business; the payee is an individual, partnership, estate, or in some cases a corporation; and the year’s reportable payments meet the threshold.
Personal payments outside a trade or business are generally not reportable on these business information returns. Employee wages belong on Form W-2 and payroll filings, not on 1099-NEC. Rents, royalties, and certain other payment types may belong on Form 1099-MISC or elsewhere. Use the current Instructions for Forms 1099-MISC and 1099-NEC rather than guessing from a blog memory.
What is the 1099-NEC dollar threshold in 2026?
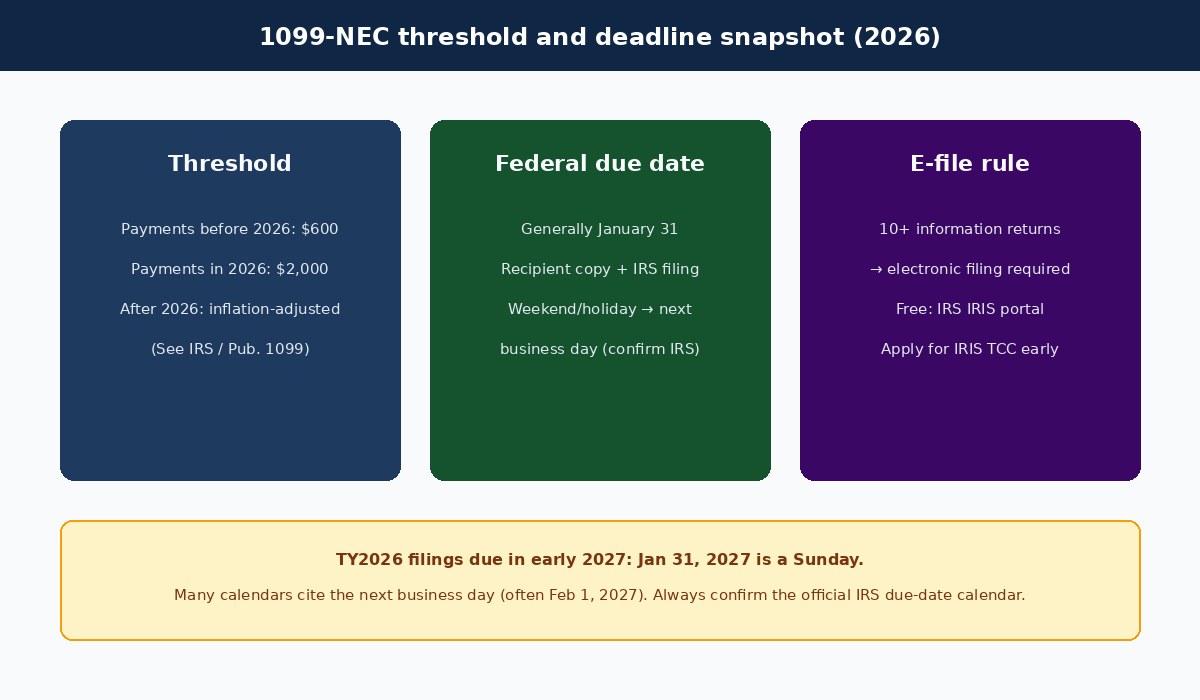
According to IRS.gov, for payments made before 2026 the Form 1099-NEC reporting threshold is $600. For payments made in 2026 the reporting threshold is $2,000. For payments made after 2026, see Publication 1099 for the inflation-adjusted reporting threshold. Many older articles and templates still say “$600” without the year split; if you are filing for 2026 calendar-year payments, use the $2,000 figure from the IRS page unless newer official guidance changes it. You must also file Form 1099-NEC when you withheld federal income tax under backup withholding rules, regardless of the payment amount.
Ops implication: set your AP or bookkeeping report to sum reportable nonemployee service payments per payee TIN for the calendar year, then compare against the threshold that applies to that year. Do not mix personal reimbursements and employee wages into the same “contractor” export.
When is Form 1099-NEC due?
Section 6071(c) and the Instructions for Forms 1099-MISC and 1099-NEC generally require you to file Form 1099-NEC on or before January 31, using either paper or electronic filing procedures (electronic filing is required once you hit the 10-return rule discussed below). Recipient copies are also generally due by January 31. If any date shown falls on a Saturday, Sunday, or legal holiday in the District of Columbia or where the return is filed, the due date is the next business day.
For tax year 2026 payments you will file in early 2027, January 31, 2027 falls on a Sunday. Many filing calendars therefore cite the next business day (often February 1, 2027). Phrase your internal deadline carefully and confirm the official IRS due-date calendar before you rely on a blog or software banner. Automatic extensions for Form 1099-NEC are limited; check Form 8809 and Publication 1099 rather than assuming you can push January work into March.
Do you need a W-9 before you file?
Yes in practice. Collect Form W-9 before the first payment whenever you can. The W-9 gives you the legal name, TIN (SSN or EIN), and federal tax classification you will copy onto Form 1099-NEC. TIN mismatches are a common source of IRS notices. If a vendor refuses to provide a W-9, pause and talk to your CPA about backup withholding and whether you should pay at all.
Store the W-9 where AP and bookkeeping can both find it. Re-request a fresh W-9 when a contractor changes legal name, TIN, or classification. For payment workflows without a full payroll suite, see best ways to pay 1099 contractors without payroll software and the accounts payable checklist.
Step-by-step: how to file 1099-NEC
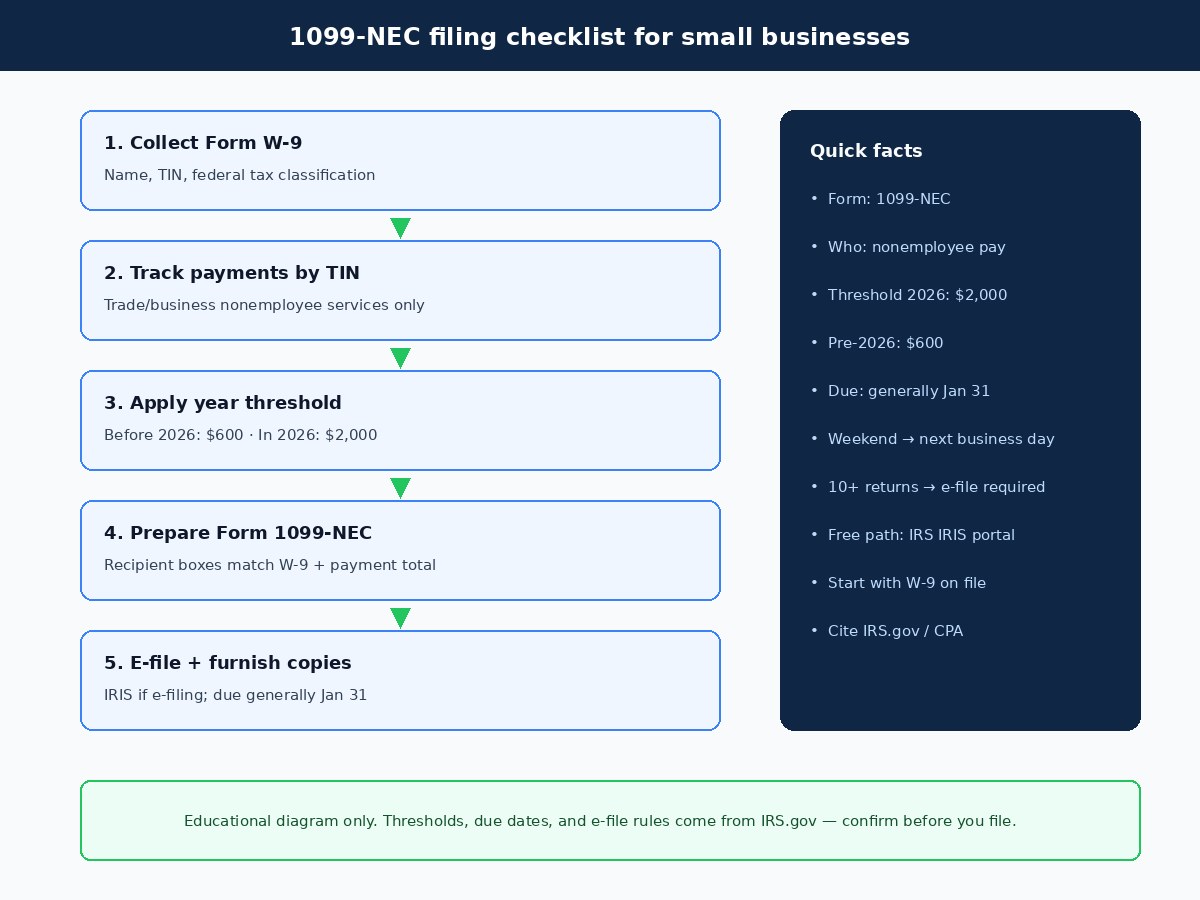
- Collect a completed Form W-9 before the first payment (or as soon as you notice it is missing).
- Record the payee’s legal name, TIN, and federal tax classification in your vendor master.
- Tag invoices as trade-or-business nonemployee services when that is what you bought.
- Run a calendar-year payment total by TIN; apply the IRS threshold for that year ($600 before 2026; $2,000 for payments made in 2026 per IRS.gov).
- Prepare Form 1099-NEC for each payee who meets the conditions. Match the W-9 name and TIN exactly.
- E-file with the IRS (IRIS Taxpayer Portal or approved software) when required or preferred, and furnish recipient copies by the due date.
- Keep copies of filed forms, W-9s, and payment exports with your year-end records.
If classification shows a corporation (including an LLC treated as a C or S corporation) and the payment is ordinary nonemployee services, you may be outside Form 1099-NEC for that payee. Confirm exceptions in IRS instructions (attorneys are a common example called out in IRS materials). For the LLC-specific decision map, see do I need to 1099 an LLC instead of re-deriving the whole classification article here.
How to e-file 1099-NEC (IRIS and the 10+ rule)
If you have 10 or more information returns, you must file them electronically. That aggregate count includes Forms W-2 e-filed with the Social Security Administration and other information returns in the same calendar year. Soft-file paper copies are not a workaround once you cross the threshold. See the IRS page on whether you are required to file a Form 1099 and its e-file notes.
The IRS Information Returns Intake System (IRIS) Taxpayer Portal lets businesses e-file Form 1099 series returns for free online. You need an IRIS Transmitter Control Code (TCC). First-time applicants should allow processing time (IRS materials often note it may take up to about 45 days), so apply well before January. IRIS can also support corrections and extension requests for supported forms. Older FIRE pathways still exist for some filers and transmitters, but for most small businesses IRIS is the clearer self-serve path. Details live on the IRS pages for e-filing with IRIS.
Bookkeeping or payroll products may e-file for you as a paid service. That can be convenient, but it does not replace your duty to keep clean W-9s and accurate payment totals. If you outsource filing, still review the draft 1099 list against your AP export before anyone hits submit.
What if you paid an LLC?
The letters “LLC” on an invoice are not enough to decide. Federal tax classification on Form W-9 drives whether ordinary nonemployee service payments stay in Form 1099-NEC scope. Disregarded entities and partnership LLCs usually remain in scope when the other conditions and threshold are met. LLCs treated as C or S corporations are generally excluded for ordinary services, with important exceptions in IRS instructions. Read the short decision map in do I need to 1099 an LLC, then return here for the filing mechanics.
How to correct a wrong 1099-NEC
If you already filed and later find a wrong amount, wrong TIN, or wrong name, file a corrected Form 1099-NEC following the correction instructions in the current Instructions for Forms 1099-MISC and 1099-NEC (and Publication 1099 for general information-return rules). IRIS supports corrections for returns filed through that system. Also send a corrected recipient copy when required. Do not invent a correction workflow from memory; the void/correct checkbox mechanics change less often than the threshold, but they still belong in the official instructions.
If the recipient got an incorrect form, they should contact you (the payer) first. As the payer, treat a contractor email about a bad 1099 as an ops ticket: pull the W-9, pull the payment export, then decide whether a correction is needed.
State filing and Combined Federal/State Filing (high level)
Some states want their own information returns or participate in Combined Federal/State Filing (CF/SF) programs that can forward certain federal filings to participating states. Rules vary by state, by form, and by whether you have nexus or payees in that state. This is YMYL territory: treat state filing as a CPA checklist item, not something to copy from a national blog. After you lock the federal 1099-NEC list, ask your tax pro which states need a separate step for your facts.
Tracking contractor payments year-round
January filing is easy when December already has a vendor master with W-9s and a payment export you trust. How you move the money (ACH, check, or card-funded bill pay) should still leave an audit trail that matches the vendor master. If you pay invoice-style contractors and vendors through a business bill-pay tool, keep the same W-9 discipline; the payment rail does not invent a filing exemption. For Melio-specific contractor payment mechanics, see can you pay contractors with Melio.
Try Melio if you want a simple way to pay contractors and vendors by ACH, check, or card-funded payments while you keep W-9 and year-end 1099 work in your books or with your CPA. Melio is a payments layer. It is not a substitute for reading IRS instructions, for e-filing Form 1099-NEC, or for employee payroll.
When the hire-employee path fits instead
If the person you are paying looks like an employee under IRS worker-classification factors (behavioral control, financial control, and type of relationship), paying them as a contractor and filing a 1099 does not fix the risk. Misclassification can cost more than a payroll subscription. Use W-2 vs 1099, then decide whether you need payroll for the role.
When you truly need W-2 payroll or a workforce tool that also helps with contractor records, compare that path separately from AP bill pay. Soft option: explore Gusto for employee payroll, and see how to pay contractors with Gusto if you want contractor payments inside a payroll-style product. For tool shopping across categories, the comparisons hub is the index.
Common 1099-NEC filing mistakes
- Waiting until mid-January to request missing W-9s.
- Using a stale $600 rule of thumb for 2026 calendar-year payments without checking IRS.gov ($2,000 for payments made in 2026).
- Filing for every LLC without reading federal tax classification (see do I need to 1099 an LLC).
- Assuming paper filing is fine after you already have 10 or more information returns.
- Mixing employee wages, owner draws, and contractor invoices in one undifferentiated export.
- Skipping recipient copies or treating the IRS e-file alone as “done.”
- Ignoring backup withholding situations that require a 1099-NEC even below the dollar threshold.
- Assuming a payment product files your 1099s unless you confirmed that service in writing.
FAQ: how to file 1099-NEC
How do I file Form 1099-NEC as a small business?
Collect W-9s, total reportable nonemployee compensation by TIN, apply that year’s IRS threshold, prepare Form 1099-NEC, then e-file (often via IRS IRIS) and furnish recipient copies by the due date. Confirm details in the Instructions for Forms 1099-MISC and 1099-NEC.
What is the 1099-NEC filing deadline?
Generally January 31 for both the IRS filing and the recipient copy. If that date falls on a weekend or holiday, use the next business day. For tax year 2026 filings due in early 2027, confirm the official IRS calendar because January 31, 2027 is a Sunday.
What is the 1099-NEC reporting threshold for 2026?
For payments made in 2026, the Form 1099-NEC reporting threshold is $2,000. For payments made before 2026 it was $600. After 2026, see Publication 1099 for any inflation-adjusted amount. Backup withholding can require filing regardless of amount.
Can I e-file 1099-NEC for free with the IRS?
Yes. The IRS IRIS Taxpayer Portal supports free electronic filing of Form 1099 series returns for businesses that obtain an IRIS TCC. If you file 10 or more information returns, e-filing is required.
Do I need a W-9 before filing 1099-NEC?
You should. The W-9 supplies the legal name, TIN, and classification you need for accurate filing and for deciding whether a corporate exception applies.
Do I still file 1099-NEC if I paid an LLC?
It depends on the LLC’s federal tax classification and the payment type. See do I need to 1099 an LLC for the classification checklist, then file when the NEC rules still apply.
How do I correct a Form 1099-NEC after filing?
File a corrected Form 1099-NEC per the current IRS instructions and furnish a corrected recipient copy when required. If you filed through IRIS, use that system’s correction flow.
Is this legal or tax advice?
No. This is educational content for U.S. small-business operators. Use IRS publications and a qualified professional for your facts.
Related reading
- Tax compliance hub
- Bill pay hub
- Payroll hub
- Comparisons hub
- Do I need to 1099 an LLC
- W-2 vs 1099
- Best ways to pay 1099 contractors without payroll software
- Can you pay contractors with Melio
- How to pay contractors with Gusto
- Accounts payable checklist for small business owners
Bottom line for ops: collect the W-9 early, track reportable payments by TIN, apply the correct year’s IRS threshold, and e-file Form 1099-NEC on time (IRIS is the free federal path for many SMBs). For paying contractors day to day while you keep compliance work with your books and CPA, Try Melio can simplify ACH, check, and card-funded bill pay.