W-2 vs 1099 is a worker-classification decision, not a form preference you pick to cut payroll taxes. If you have the right to control what is done and how it is done, the worker is generally an employee and you report wages on Form W-2. If you control only the result and the worker runs an independent trade, they are generally an independent contractor and you may need Form 1099-NEC when reporting thresholds are met. A contract that says “contractor” does not override the facts.
Disclosure: This guide is educational for U.S. small business owners. It is not legal, tax, accounting, or employment advice. Classification and reporting rules depend on facts and can change. Confirm current IRS guidance and your state rules, and work with a qualified professional before you hire, reclassify, or file.
Research note: Classification factors and Form SS-8 guidance were checked on IRS: Independent contractor or employee? on October 28, 2026. The 2026 Form 1099-NEC payment threshold of $2,000 (vs $600 for payments made in 2025) was checked in Publication 15 (2026) and the IRS page Am I required to file a Form 1099?. Re-check before you file.

Quick answer: W-2 vs 1099 in plain ops language
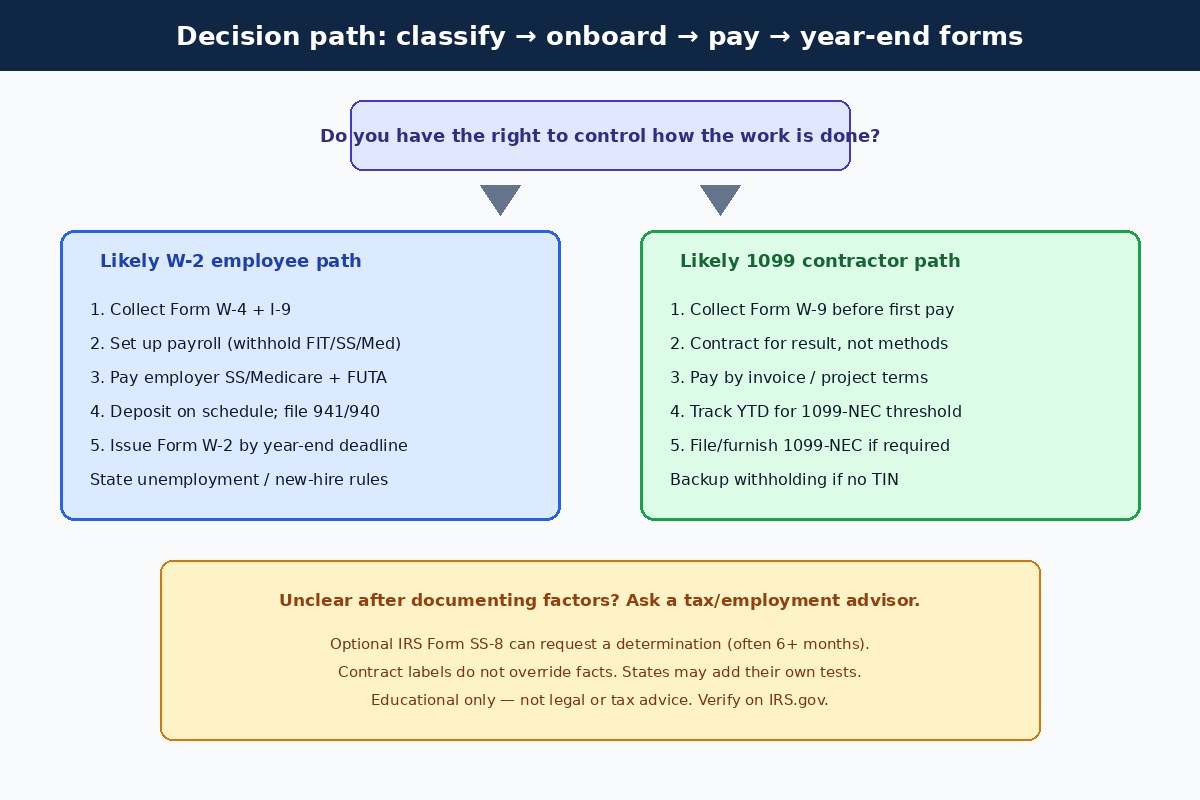
Takeaway: Classify the relationship first using IRS common-law factors; then use Form W-2 for employees and Form 1099-NEC for nonemployee compensation when required.
Owners often ask “Should I put this person on a 1099?” as if the form is a hiring mode. The IRS looks at the degree of control and independence across behavioral, financial, and relationship facts. Employees generally trigger withholding of federal income tax plus Social Security and Medicare, matching employer payroll taxes, unemployment tax, Form W-2, and often state payroll registration. Independent contractors generally invoice you, pay their own self-employment taxes, and may receive Form 1099-NEC when your trade-or-business payments hit the annual threshold.
If you are still building the hire-or-contract workflow, pair this page with payroll basics, tax compliance, and our contractor payment guides linked below.
Who this guide is for
Takeaway: Use this if you are about to make an offer, convert a trial helper, or clean up mixed W-2 / 1099 habits before year-end.
- U.S. small business owners hiring a first employee or recurring contractor
- Ops or finance leads drafting job posts and offer letters
- Owners who heard “just 1099 them” and want an IRS-aligned checklist instead
- Teams comparing payroll software vs contractor payment tooling after classification is clear
What Form W-2 means for a small business
Takeaway: Form W-2 reports wages for employees; the employer withholds and remits employment taxes and generally pays the employer share of Social Security and Medicare.
Under common-law rules, a worker is generally your employee if you have the right to control what will be done and how it will be done — even when you give freedom of action day to day. What matters is the right to control the details. Corporate officers who work in the business are employees of the corporation.
For employees you typically:
- Collect Form W-4 and complete Form I-9 for work eligibility
- Withhold federal income tax plus the employee share of Social Security and Medicare
- Pay the employer share of Social Security and Medicare, and generally Federal Unemployment Tax (FUTA)
- Deposit on the IRS schedule that applies to you and file employment tax returns (for example Form 941 and Form 940)
- Furnish and file Form W-2
Publication 15 (2026) lists the 2026 Social Security wage base at $184,500, with Social Security tax at 6.2% each for employer and employee and Medicare at 1.45% each (no wage base for Medicare). Those published rates are the federal payroll-tax floor — benefits, state unemployment, workers’ compensation, and admin sit on top. See payroll when you are ready to run the first paycheck.
What Form 1099-NEC means for a small business
Takeaway: Form 1099-NEC reports nonemployee compensation to independent contractors; it is the usual information return for services, not outdated “1099-MISC for everything.”
An independent contractor generally controls the means and methods of the work. You control the result. Doctors, lawyers, and others in an independent trade who offer services to the public are often contractors — but every case turns on facts, not job titles.
You generally must report nonemployee compensation on Form 1099-NEC when all of these apply (IRS reporting-payments guidance): you paid someone who is not your employee; the payment was for services in your trade or business; the payee is an individual, partnership, estate, or in some cases a corporation; and your reportable payments to that payee meet the annual threshold. Backup withholding has separate rules when you lack a correct TIN.
Form 1099-MISC still exists for other categories (rents, royalties, certain other income, and more). For most service payments to contractors, think 1099-NEC. Collect Form W-9 before the first payment so you have a TIN on file. For payment ops after classification, see ways to pay 1099 contractors without payroll software, track contractor payments with a spreadsheet, and best 1099 software for small business.
Side-by-side: W-2 employee vs 1099-NEC contractor
Takeaway: Employees cost more in payroll tax and admin; contractors shift tax filing to the worker — but only when the facts support contractor status.
| Topic | W-2 employee | 1099-NEC contractor |
|---|---|---|
| Core IRS idea | You may control what and how | You control the result; worker controls means/methods |
| Primary form | Form W-2 | Form 1099-NEC (when threshold met) |
| Federal income tax | You withhold from wages | Worker generally estimates/pays own tax |
| Social Security / Medicare | Withhold employee share; pay employer share | Worker generally pays self-employment tax |
| Unemployment tax | Employer FUTA (and often state UI) | Generally not employer FUTA for true contractors |
| Benefits | Often offered (not required federally for all SMBs) | Usually not employee benefits |
| Tools / expenses | Often employer-provided or reimbursed under plan | More often worker’s unreimbursed business costs |
| Payment rhythm | Regular wage / salary payroll | Invoice, project, or time-and-materials |
| Onboarding docs | W-4, I-9, new-hire reporting | W-9, written SOW/contract |
IRS common-law factors: behavioral, financial, relationship
Takeaway: Weigh all three categories; there is no magic scorecard that “makes” someone a contractor if you still control how the work is done.

The IRS groups evidence of control and independence into three categories:
- Behavioral: Do you control (or have the right to control) what the worker does and how they do it — schedule, location, tools, assistants, sequence, training?
- Financial: Who bears unreimbursed expenses? Who invests in tools? Can the worker market services to others? Is pay a regular wage or a project/fee with profit-or-loss risk?
- Type of relationship: Written contracts help document intent but do not bind the IRS. Benefits, permanency, and whether the work is a key activity of your business all matter.
Remote work does not automatically create contractor status. If you can control what will be done and how it will be done, a remote worker can still be your employee under common-law rules.
2026 reporting thresholds and dates to know
Takeaway: For payments made in 2026, the Form 1099-NEC nonemployee compensation reporting threshold is generally $2,000; for payments made in 2025 it was $600.
Publication 15 (2026) and the IRS information-return page state that P.L. 119-21 raises the information reporting threshold for certain payments (including Forms 1099-NEC and 1099-MISC in covered categories) from $600 to $2,000 for payments made after calendar year 2025. The threshold is scheduled to adjust for inflation for calendar years after 2026. Always confirm the Instructions for Forms 1099-MISC and 1099-NEC for the year you are filing.
Other ops notes (high level):
- Backup withholding can require a Form 1099-NEC even below the ordinary threshold when federal income tax was withheld under backup withholding rules.
- If you file 10 or more information returns, electronic filing is generally required (combine nearly all information return types, including Forms W-2 filed with the SSA).
- The IRS IRIS Taxpayer Portal is a free option many small businesses use to e-file Form 1099 series.
Exact furnish and file due dates move with weekends and holidays. Use the current year’s IRS instructions and Pub. 509 calendar rather than memorizing a blog date.
Cost shape: taxes, benefits, and admin
Takeaway: Compare total cost of a correct classification — not the sticker rate of “contractor vs employee” after ignoring taxes you still owe if you guessed wrong.
Employee path costs usually include the employer share of Social Security and Medicare on taxable wages, FUTA (subject to wage base and credits), state unemployment, workers’ compensation where required, payroll software or accountant time, and any benefits you offer. Contractor path costs usually include the agreed fee, payment tooling, W-9 collection, year-end 1099 prep, and the management cost of a looser schedule. Contractors often bill higher hourly or project rates because they cover self-employment tax and their own benefits.
Do not invent a single “employees cost X% more” number for your books. Run a worksheet with (1) published federal rates from Pub. 15, (2) your state unemployment rate, (3) benefits you actually offer, and (4) the contractor’s quoted fee. Misclassification risk is part of the cost model: if the IRS later treats the worker as an employee, you may owe employment taxes (see IRC section 3509 rates discussed in Pub. 15) and lose the clean contractor story you budgeted for.
When each path usually fits
Takeaway: Choose W-2 when the role needs ongoing direction inside your business; choose 1099 when you are buying a defined result from someone in business for themselves.
W-2 often fits when: the person works set hours you define, uses your systems as an insider, represents your brand day to day, needs training in your methods, or performs a core ongoing function you direct. First full-time bookkeeper, store associate, or customer-success hire usually lands here.
1099 often fits when: you buy a project or specialized deliverable, the worker markets the same services to others, brings their own tools and methods, invoices multiple clients, and can profit or lose on the engagement. A one-time website redesign by an agency or a fractional consultant with their own practice is a common example — still document the factors.
Misclassification risk and what to do if unclear
Takeaway: If facts are mixed, document them and get advice; Form SS-8 can request an IRS determination, but it can take at least six months.
If you treat an employee as an independent contractor without a reasonable basis, you may be held liable for employment taxes for that worker. Pub. 15 summarizes section 3509 rates that can apply in some reclassification situations, and notes that intentional disregard has different outcomes. Relief under Section 530 may apply in limited circumstances when you had a reasonable basis and filed consistently — relief from employment tax is not the same as a ruling that the worker “is” a contractor. The Voluntary Classification Settlement Program (VCSP) is an optional IRS program for eligible taxpayers who want to reclassify workers prospectively with partial relief; apply with Form 8952 if you explore that path with an advisor.
Either the business or the worker may file Form SS-8 to request a determination of worker status for federal employment tax purposes. The IRS notes determinations can take at least six months. Incomplete forms are returned. Pending worker-classification litigation can affect whether the IRS will rule.
State nuance caveat: Some states use additional or different tests (for example ABC-style tests) for wage-and-hour or unemployment purposes. Passing a federal common-law analysis does not automatically clear every state rule. Check your state labor and tax agencies.
Paying each type after you classify
Takeaway: Payroll software fits W-2; contractor payment ops fit 1099 — after classification is settled, not as a way to force the label.
For employees, you need a payroll process that withholds, deposits, and files. Many small teams use a payroll provider for that stack. Soft option if you are hiring on the W-2 path: Gusto (partner link; we may earn a commission at no extra cost to you). Compare features against your headcount and contractor mix; Gusto can also support contractor payments in some plans — see how to pay contractors with Gusto.
For contractors, collect W-9s, pay against invoices, track year-to-date totals toward the 1099-NEC threshold, and keep records for IRIS or your accountant. Some owners pay contractor invoices through bill-pay tools; Melio can fit that AP angle when the relationship is already a true vendor/contractor arrangement — see Can you pay contractors with Melio? Classification still comes first.
Checklist before you make an offer
Takeaway: Write down the factors, pick the path, then send the matching paperwork — do not send a contractor agreement for an employee-shaped role.
- List behavioral, financial, and relationship facts for this specific role (save the notes)
- Confirm whether the work is ongoing core ops or a defined deliverable
- If employee: prepare W-4, I-9, state new-hire reporting, payroll setup
- If contractor: prepare W-9, SOW with deliverables and payment terms, YTD tracking
- Check state tests that may differ from federal common law
- If still unclear: pause the offer language and talk to a CPA or employment counsel; consider SS-8 only with eyes open on timing
- Schedule year-end form prep (W-2 or 1099-NEC) on the calendar now
FAQ
What is the difference between W-2 and 1099?
Form W-2 reports wages for employees. Form 1099-NEC reports nonemployee compensation for independent contractors when reporting rules are met. The form follows the classification; it does not create it.
Can I choose 1099 to save on payroll taxes?
No. If the facts show an employee relationship, treating the worker as a contractor to avoid employment taxes can create liability for those taxes and related penalties. Budget the correct path instead.
Is 1099-MISC still used for contractor services?
Nonemployee compensation for services is generally reported on Form 1099-NEC. Form 1099-MISC covers other payment types such as rents and royalties. Use the IRS instructions for the tax year you are filing.
What is the 1099-NEC threshold for 2026?
For payments made in 2026, the IRS states the reporting threshold for Form 1099-NEC nonemployee compensation is generally $2,000 (it was $600 for payments made in 2025). Confirm the year’s instructions before you file; the threshold is set to adjust for inflation after 2026.
What is Form SS-8?
Form SS-8 asks the IRS to determine worker status for federal employment tax and income tax withholding purposes. Either the firm or the worker may file. The IRS notes it may take at least six months.
Do remote workers count as employees?
They can. Location alone does not decide status. If you have the right to control what is done and how it is done, a remote worker can be your employee under common-law rules.
What happens if I misclassify a worker?
You may owe employment taxes for that worker. Depending on facts, section 3509 rates, Section 530 relief, or the Voluntary Classification Settlement Program may be relevant. Get professional advice for your situation; do not rely on a blog for settlement strategy.
Do I need payroll software if I only have contractors?
Not necessarily for pure contractors, but you still need W-9 collection, payment records, and 1099-NEC filing when required. Many teams use contractor-friendly payment tools or 1099 software; see best 1099 software and paying contractors without payroll software.
Related reading
- How to pay contractors with Gusto
- Can you pay contractors with Melio?
- Best ways to pay 1099 contractors without payroll software
- Track contractor payments spreadsheet
- Best 1099 software for small business
- Payroll pillar · Tax compliance pillar · Comparisons · Bill pay
Official IRS references
- Independent contractor (self-employed) or employee?
- Reporting payments to independent contractors
- Publication 15 (2026), Employer’s Tax Guide
- Am I required to file a Form 1099 or other information return?
- Completing Form SS-8
Next step when the W-2 path is real
If your checklist points to an employee, set up payroll before the first payday — withholdings, deposits, and year-end W-2s are part of the job. Soft option: try Gusto (partner link; we may earn a commission at no extra cost to you). If the role is a true contractor engagement, start with a W-9, a clear SOW, and YTD tracking toward the 2026 1099-NEC threshold, and use contractor payment with Gusto or non-payroll contractor pay options as fits. Re-read the IRS common-law factors any time the working relationship changes.