Disclosure: This guide is educational and may include affiliate links. We may earn a commission if you sign up through our Gusto partner link, at no extra cost to you. It is not legal, tax, accounting, or financial advice. Whether your LLC needs payroll depends on tax elections, worker classification, and state rules. Verify details with the IRS, your state agencies, and a qualified CPA or attorney before you act.
Forming an LLC answers a legal and liability question. It does not automatically create a payroll department. The Ops question most owners actually mean is: when do I need withholding, deposits, W-2s, and state wage accounts—and when is an owner’s draw or a contractor payment enough? In 2026 the useful answer still starts with two facts you can write on one page: how the LLC is taxed for federal purposes, and whether anyone is a W-2 employee (including you as an S-corp owner-employee).
Quick answer: do you need payroll for your LLC?
Often no if you are a single-member LLC taxed as a disregarded entity, you have no employees, and you only move profit to yourself as owner’s draws. Usually yes if you hire W-2 employees. Usually yes for working owners when the LLC is taxed as an S corporation and reasonable compensation is paid as wages. Contractor-only shops need payment tracking and 1099 workflows when required, which is related to payroll Ops but is not the same as running employee payroll. For how owner pay works by tax election, see how to pay yourself from an LLC.
| Situation | Likely payroll need |
|---|---|
| Single-member LLC, disregarded, no employees | Often draws + bookkeeping; W-2 payroll for the owner usually not required |
| LLC paying 1099 contractors only | Contractor pay + 1099 process; employee payroll optional until W-2 wages exist |
| LLC with W-2 employees | Yes—full payroll process |
| LLC taxed as S-corp, owner works in the business | Yes—reasonable W-2 salary via payroll, then distributions as advised |
| Multi-member partnership LLC, partners only | Often draws/guaranteed payments under partnership rules; confirm with CPA before inventing W-2s |
Who this guide is for
Use this if you just formed an LLC and are unsure whether Gusto or another payroll product is mandatory, if you are about to hire contractors or a first employee, or if you are weighing an S-corp election and want the payroll implications in plain Ops language. Skip this if you need a binding tax election model or a reasonable-compensation study; those belong with a CPA. This article is a decision map for small US businesses, not a substitute for Forms 941/940 instructions or Form 2553 advice.
LLC legal entity vs tax status
State LLC formation creates a legal entity. Federal tax treatment is a separate lever. By default, a single-member LLC is often a disregarded entity (frequently reported like a sole proprietorship on the owner’s return). A multi-member LLC is often taxed as a partnership. The LLC can elect corporate taxation, and when eligible it may elect S corporation status. Those choices change whether owner pay looks like draws, partnership payments, W-2 wages, or a mix—and whether “payroll” is an optional software purchase or a compliance requirement.
Write a one-page ops note: current federal tax treatment, election dates if any, who may authorize owner transfers, and whether any workers are classified as employees. Update the note when your CPA files an election. Buying payroll software before that note exists is how teams create W-2 noise they did not intend—or miss wage filings they did.
No employees: when draws replace payroll
If you are the only person in the business, the LLC is disregarded for tax purposes, and you are not electing S-corp wages, you typically transfer cash as an owner’s draw against equity. That transfer is usually not processed as a deductible W-2 wage of the LLC. You still need clean books, separated bank accounts, and a plan for income tax and (in many sole-prop-style situations) self-employment tax on profit. A draw can feel like a paycheck; tax timing still follows your return and estimated-tax calendar, not the day you clicked transfer.
Ops habits that keep a draws-only LLC readable:
- Separate business and personal accounts and cards.
- Schedule draws on a cadence so cash forecasting works.
- Label transfers as owner draws in accounting software, not “salary,” unless wages truly apply.
- Keep a tax reserve for estimated payments your CPA recommends.
- Reconcile monthly so draws do not silently erase working capital.
Multi-member LLCs taxed as partnerships usually use draws or distributions under the operating agreement, and sometimes guaranteed payments. Those are partnership concepts, not identical to W-2 payroll. Confirm labels with your CPA before you invent employee payroll for partners who are not employees under your tax setup.
Hiring contractors: 1099 workflows, not employee payroll
Paying freelancers or agencies does not automatically mean you need employee payroll software. Contractor Ops usually means collecting W-9s, tracking payments, classifying workers correctly, and issuing Form 1099-NEC when thresholds and rules require it. Misclassification is the expensive mistake: treating someone you control like an employee as a 1099 contractor can create back taxes and penalties. Use W-2 vs 1099 when roles are ambiguous, and keep contractor payments in their own process so they do not collide with owner draws.
Some payroll platforms also pay contractors and help with 1099 filing. That convenience is useful, but it is still a contractor workflow. You can often pay contractors with bank transfers and a year-end 1099 process without running a full employee payroll calendar—until you add W-2 wages.
Hiring W-2 employees: when payroll becomes mandatory Ops
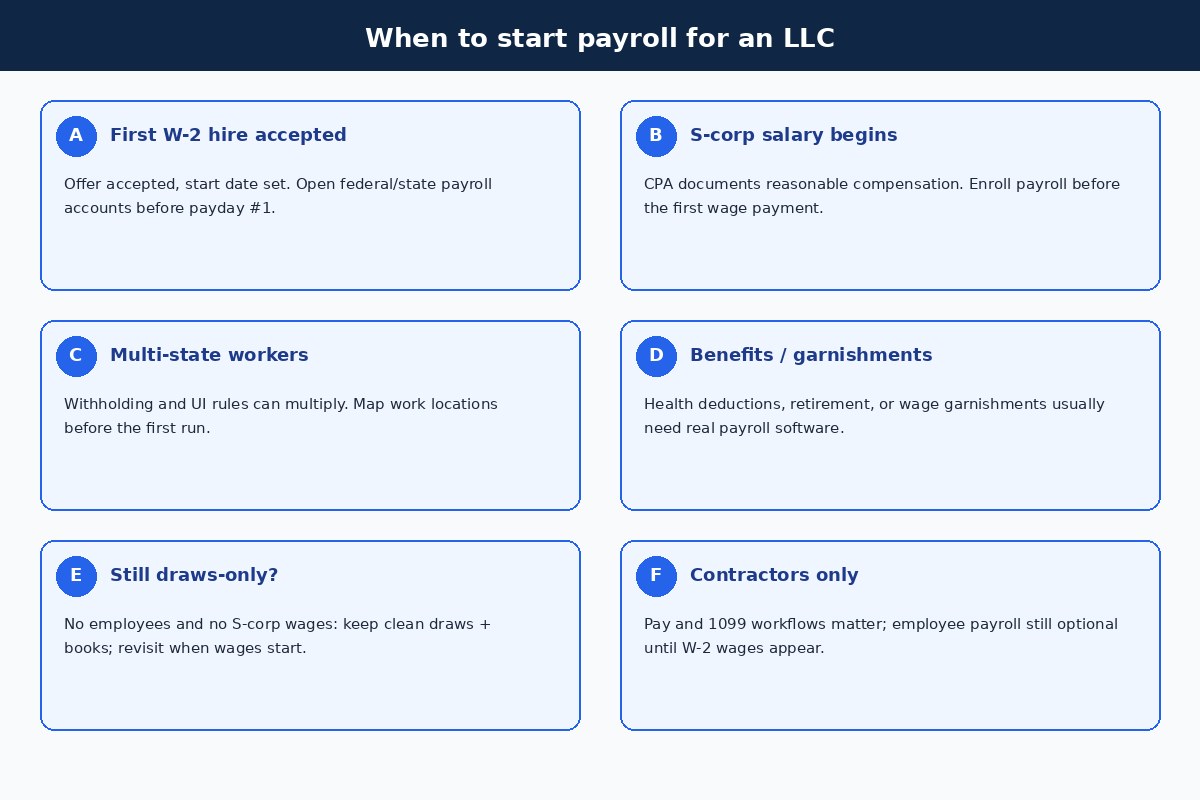
Once someone is a W-2 employee, you need a payroll process: collect Form W-4, complete Form I-9, calculate federal income tax withholding and FICA, deposit employment taxes on schedule, file Forms 941 (and 940 when unemployment tax applies), issue pay stubs, and deliver Form W-2 at year-end. States add withholding accounts, unemployment insurance, and sometimes local taxes. The first-employee tax map is in payroll taxes for your first employee; the runbook is in how to run payroll for your first employee; onboarding steps live in the new-hire payroll checklist.
Register state accounts before the payday that creates an obligation. Late UI or withholding registration is a common first-hire stumble. Put the employee’s work location on the ops note—remote multi-state work can multiply registrations.
S-corp owner salary: payroll for the owner-employee
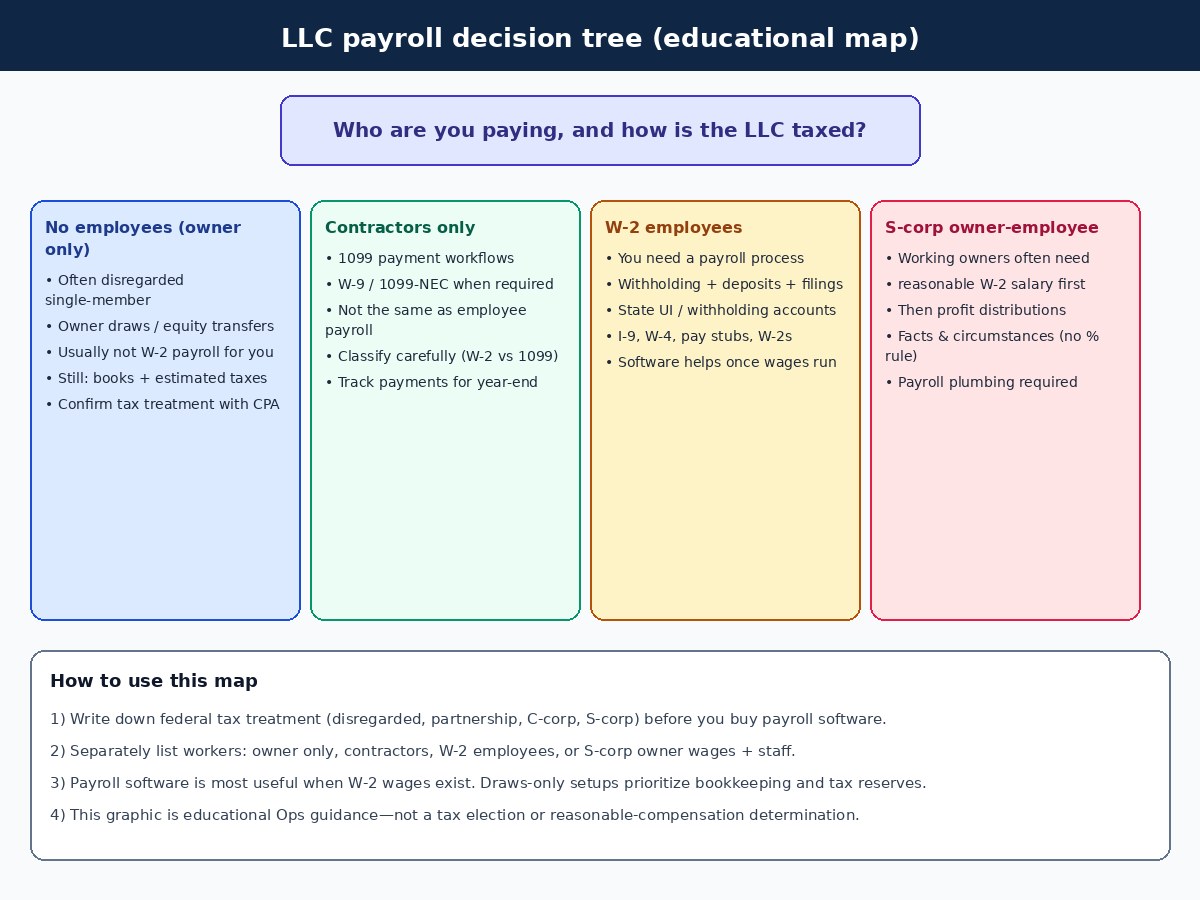
When an LLC is taxed as an S corporation, shareholders who perform services are generally employees for the wages they earn. The IRS expects reasonable compensation for those services before profit is taken as distributions. Wages run through payroll with income and employment tax withholding. Distributions follow S-corp basis and reporting rules and are not a substitute for wages when services are substantial.
“Reasonable” is a facts-and-circumstances analysis: role, hours, skills, comparable pay, and company history of wages versus distributions. There is no single IRS percentage-of-profit formula that safely replaces that analysis. Document salary with a CPA, then run it on a real payroll calendar. Owner-only S-corp wages still need the same plumbing as a first hire: EIN as needed, state accounts where required, deposits, 941/940 as applicable, and a W-2.
State registration notes
Federal EIN and federal deposit schedules are only half the story. Most states require employer withholding accounts once you have taxable wages, and unemployment insurance registration when you have covered employment. Deadlines and thresholds vary. Some localities add income or payroll taxes. Before payday one:
- Confirm where the employee (or owner-employee) performs services.
- Open or verify state withholding and UI accounts in those jurisdictions.
- Check new-hire reporting deadlines.
- Align pay frequency with deposit schedules so cash is reserved.
- Ask your CPA or payroll provider which local taxes apply.
If you only take draws and have no wages, many employer wage accounts stay dormant—until the first W-2 payday or S-corp salary starts. Do not assume “LLC” alone registered you for payroll taxes.
Payroll software vs CPA: who owns which decision
Your CPA (or enrolled agent) owns tax elections, reasonable-compensation judgment, estimated-tax planning, and year-end return strategy. Payroll software owns calculation, filing assistance in supported jurisdictions, pay stubs, and onboarding workflows once wages exist. Software does not invent the correct election for you. A CPA does not need to click “run payroll” every biweekly cycle if a reliable system is configured.
Gusto is one option small US teams use when W-2 wages are real—owner salary, staff, or both. Compare features, state coverage, and price for your headcount in Gusto vs QuickBooks Payroll and best payroll software for 1 to 5 employees. Confirm current pricing and supported states on the vendor’s site before you enroll. More payroll guides live on the payroll hub.
Common mistakes
Assuming every LLC must buy payroll on day one. Draws-only disregarded entities often need bookkeeping and tax reserves first. Fake W-2s create filing chores without fixing estimated taxes.
Skipping payroll after an S-corp election. Working owners who take only distributions invite reasonable-compensation scrutiny. Set salary with a CPA and run it through payroll.
Treating contractors as a payroll substitute for employees. Control, hours, and tools can push a role into employee territory. Classification comes before software choice.
Late state accounts. Federal setup without state UI/withholding is incomplete for most first wages.
Mixing Melio-style bill pay with payroll decisions. Paying vendors is AP. Paying W-2 wages is payroll. Keep the clusters separate so you do not buy the wrong tool for the job.
Inventing salary percentage rules from social media. Facts, comparable pay, and professional judgment beat viral formulas.
LLC payroll decision checklist
- Write down federal tax treatment and any election dates.
- List who you pay: owner only, contractors, W-2 employees, S-corp owner wages.
- If draws-only: separate banks, draw cadence, estimated-tax reserve, monthly reconcile.
- If contractors: W-9s, classification review, payment log, 1099 process when required.
- If W-2 wages: EIN, state withholding/UI, W-4/I-9, deposit calendar, payroll method.
- If S-corp owner-employee: CPA-documented reasonable salary before distributions.
- Map work locations for multi-state risk before payday one.
- Choose software only after wages (or imminent wages) exist.
- Store election forms, payroll returns, and classification notes in one folder.
- Revisit the map when you hire, change elections, or add states.
FAQ
Do all LLC owners need payroll?
No. Many single-member disregarded LLCs with no employees use owner draws without running the owner on W-2 payroll. Payroll becomes important when you have employees, when S-corp owner-employee wages apply, or when state rules require wage reporting for your facts.
Is paying contractors the same as payroll?
No. Contractor payments use different forms and tax mechanics than employee wages. You still need classification discipline and 1099 reporting when required. Employee payroll adds withholding, employment taxes, and W-2s.
Does an S-corp LLC need payroll for the owner?
If you work in the business, you generally need reasonable W-2 compensation through payroll before taking profit distributions. Confirm the amount and timing with a CPA. There is no universal percentage safe harbor.
Can I run payroll myself in a spreadsheet?
Some micro-employers do manual payroll carefully. Error rates on deposits, multi-state rules, and year-end forms rise quickly. Software is usually worth it once you have regular W-2 wages, benefits deductions, or more than one jurisdiction.
When should I start payroll relative to a hire date?
Open federal and state accounts and choose a payroll method before the first payday that creates wage tax obligations—ideally as soon as the offer is accepted and the start date is firm. See the new-hire payroll checklist.
Do I need payroll software if I only take owner draws?
Usually not for the draws themselves. Prioritize bookkeeping and estimated taxes. Revisit payroll tools when you add W-2 employees or begin S-corp owner wages.
Should I talk to a professional before electing S-corp status?
Yes. Model wages, employment taxes, filing costs, state rules, and administrative burden with a CPA before Form 2553. This article does not recommend an election.
Where does Gusto fit?
When payroll is a real operating workflow—paying employees, onboarding, contractor payments alongside wages, tax filing support in covered states—Gusto is one platform worth comparing. Preview a run and verify terms on Gusto’s site before you enroll.
Related reading
- How to pay yourself from an LLC
- Payroll taxes for your first employee
- New-hire payroll checklist
- How to run payroll for your first employee
- W-2 vs 1099
- Gusto vs QuickBooks Payroll
- Best payroll software for 1 to 5 employees
- Payroll hub
Try Gusto when LLC payroll is real
If your LLC has W-2 employees, S-corp owner wages, or both, Gusto is a practical payroll platform to evaluate for small US teams. Use it to run wages on schedule, support onboarding, and keep filings organized in supported states—after your CPA confirms the tax path.
Try Gusto (partner link). We may earn a commission at no extra cost to you. Confirm pricing, tax filing services, and state coverage on Gusto’s official pages before you enroll.
Again: this article is educational only. It is not tax, legal, or accounting advice. LLC elections, worker classification, reasonable compensation, and payroll deposits depend on your facts. Verify IRS guidance and state rules with a qualified professional before you change how you pay yourself or your team.