Disclosure: This guide is educational and may include affiliate links. We may earn a commission if you sign up through our Gusto partner link, at no extra cost to you. It is not legal, tax, accounting, or financial advice. Federal and state payroll rules change; verify requirements with IRS Publication 15 (Circular E), your state agencies, and a qualified professional before you act.
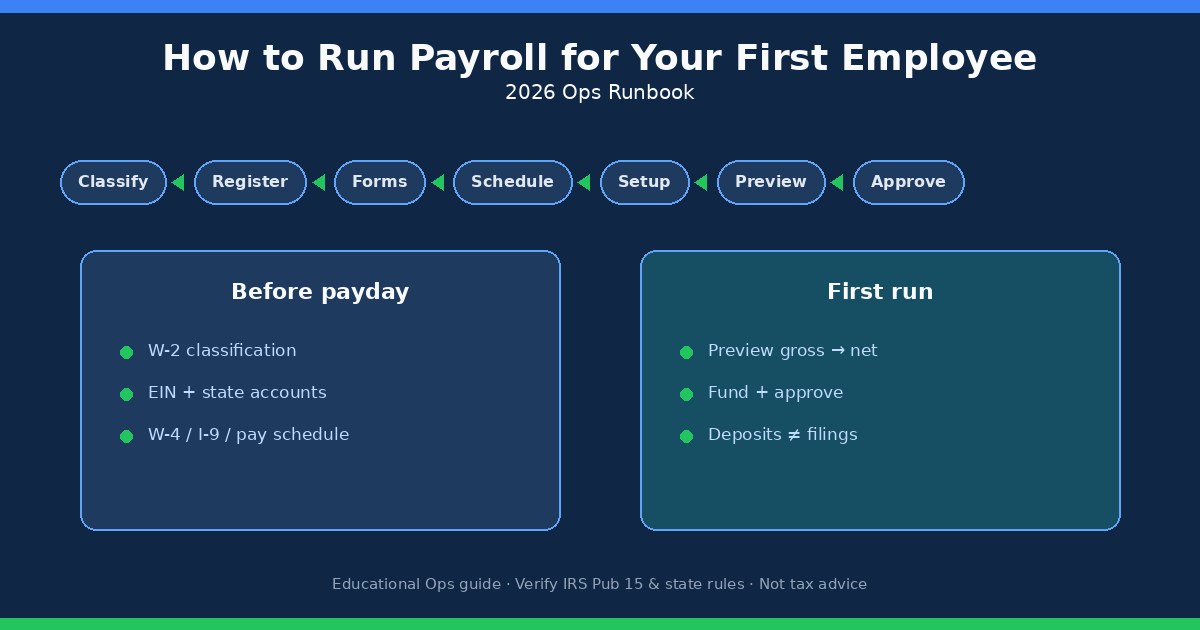
Running payroll for your first employee means confirming classification, opening employer tax accounts, collecting onboarding forms, choosing a legal pay schedule, calculating wages and deductions, paying on time, and keeping deposits and filings on separate calendars. A payroll service can automate much of the math, but you still enter accurate data and review every run. This 2026 Ops runbook walks that path end to end for a typical US small business. For day-zero checklists and tax-rate maps, use the linked companion posts instead of treating this page as a second copy of those guides.
Quick answer: how do you run payroll for a first employee?
Confirm the worker is a W-2 employee, get your federal EIN and required state or local employer accounts, collect Form W-4 and complete Form I-9, set a compliant pay schedule and rates, then set up payroll software (or a documented manual process). Preview gross pay, withholdings, employer taxes, net pay, and bank funding before you approve the first payday. After payday, deposit employment taxes on your IRS schedule and keep quarterly and year-end filings on a second calendar. Pair this runbook with the new hire payroll checklist and payroll taxes for your first employee.
Before you hire: classification and basics
Settle employee versus contractor status before you promise a pay routine. A worker who should receive a W-2 generally works under your direction inside your business; a genuine contractor runs an independent trade and controls more of how the work is done. The label in a contract does not decide the question. Misclassification can affect withholding, FICA, unemployment insurance, overtime, workers’ compensation, and year-end forms.
If this is your first hire and the person works regular hours, follows your instructions, uses your systems, and fills an ongoing role, pause before treating them as a 1099 contractor. Review the facts with a CPA or employment adviser when the role is ambiguous. Side-by-side factors are in W-2 vs 1099 for small business owners. If you are still unsure whether your LLC needs payroll at all, start with do I need payroll for my LLC? and return here when a W-2 hire is real.
Write down the employee’s legal name, address, start date, pay rate, and job status; your federal, state, and local employer account IDs; the pay period, payday, payment method, and who approves hours; and a simple time-tracking method if the worker is hourly. Your first payday should not be your first attempt at the math—run a preview early.
Registrations: federal, state, local, and new-hire reporting
Your federal Employer Identification Number (EIN) identifies the business for federal employment taxes. Keep the confirmation with core records. Separately register for state income-tax withholding and state unemployment insurance when your work location requires it. Some cities and counties add local employer taxes. A remote employee can create obligations in the employee’s work state even when your office sits elsewhere.
Business formation paperwork often does not open payroll accounts. Before the first run, confirm:
- Federal EIN and federal payroll tax setup (including EFTPS enrollment when you will deposit yourself).
- State withholding and unemployment registration for each relevant work state.
- Local employer tax registration, if applicable.
- Workers’ compensation coverage required by the work state.
- State new-hire reporting for the employee’s work location (deadlines and portals vary; the federal new-hire directory is a starting map, not the filing itself).
Check federal and state workplace poster rules for physical sites and any required digital notices for remote staff. The Department of Labor’s wage-and-hour resources are a useful federal starting point; state labor agencies still need their own review.
Forms and employee records
Have the employee complete Form W-4 so you can calculate federal income-tax withholding. Do not tell the worker what to enter; point them to IRS instructions or a tax professional if they have personal tax questions. Complete Form I-9 for employment eligibility: the employee generally finishes Section 1 by the first day of work for pay, and you generally finish Section 2 within three business days of the start date. Use current USCIS Form I-9 instructions. I-9 verifies identity and work authorization; it is not a payroll-tax form, so keep that distinction clear in your files.
Your employee file usually also holds legal contact details, pay rate and status, direct-deposit authorization, state withholding certificates where required, benefits elections, emergency contacts, and approved time or leave records. Protect identity and bank data. For hourly staff, retain hours worked, pay-period dates, regular and overtime wages, deductions, and the date wages were paid. IRS employment-tax recordkeeping guidance and state wage rules set expectations for how long to keep materials—store them so you can pull one payroll run without rebuilding your books.
Pay schedule and rates
Choose a regular pay schedule before work starts. Weekly, biweekly, semimonthly, and monthly are common, but states may limit which frequencies are allowed for certain workers. Biweekly pay usually produces 26 paychecks a year; semimonthly usually produces 24. Document the pay-period dates, the regular payday, the timesheet cutoff, and how bonuses, commissions, reimbursements, and leave appear on the stub.
Build bank and approval lead time into the calendar. Direct deposit often needs several business days; weekends and holidays shrink the window. For nonexempt hourly workers, federal overtime under the Fair Labor Standards Act is generally one and one-half times the regular rate for hours over 40 in a workweek, and some states are stricter. Use the highest applicable minimum wage among federal, state, and local rates. Put the schedule in writing before day one.
Software setup: manual vs payroll platform
You can run one-employee payroll manually with tax tables, deposits, filings, stubs, and year-end forms. That can work for a simple salaried hire when you have time and confidence. The weak point is repetition: every cycle is another chance to miss overtime, an outdated table, a state filing, or a deposit date.
| Approach | What you still own | Where it can fit | Main concern |
|---|---|---|---|
| Manual payroll | Calculations, payments, deposits, filings, records, W-2s | One simple employee, hands-on owner | Deadlines and errors stay entirely yours |
| Payroll software | Data quality, approvals, funding, review | Teams that want repeatable runs and filing support | Fees plus correct setup |
| Full-service bureau | Inputs, approvals, understanding of coverage | Owners who want less admin workload | You still review accuracy and scope |
For a first hire—especially hourly, multi-state, benefits-eligible, or overtime-prone—software is usually easier to evaluate than a year of messy records. Compare feature scope in best payroll software for 1 to 5 employees and product differences in Gusto vs QuickBooks Payroll. When you configure software, add the employee, tax accounts, pay schedule, bank funding, and any benefit deductions before the first preview. Ask the provider which jurisdictions it files for and what still falls on you.
Preview and approve the first payroll run
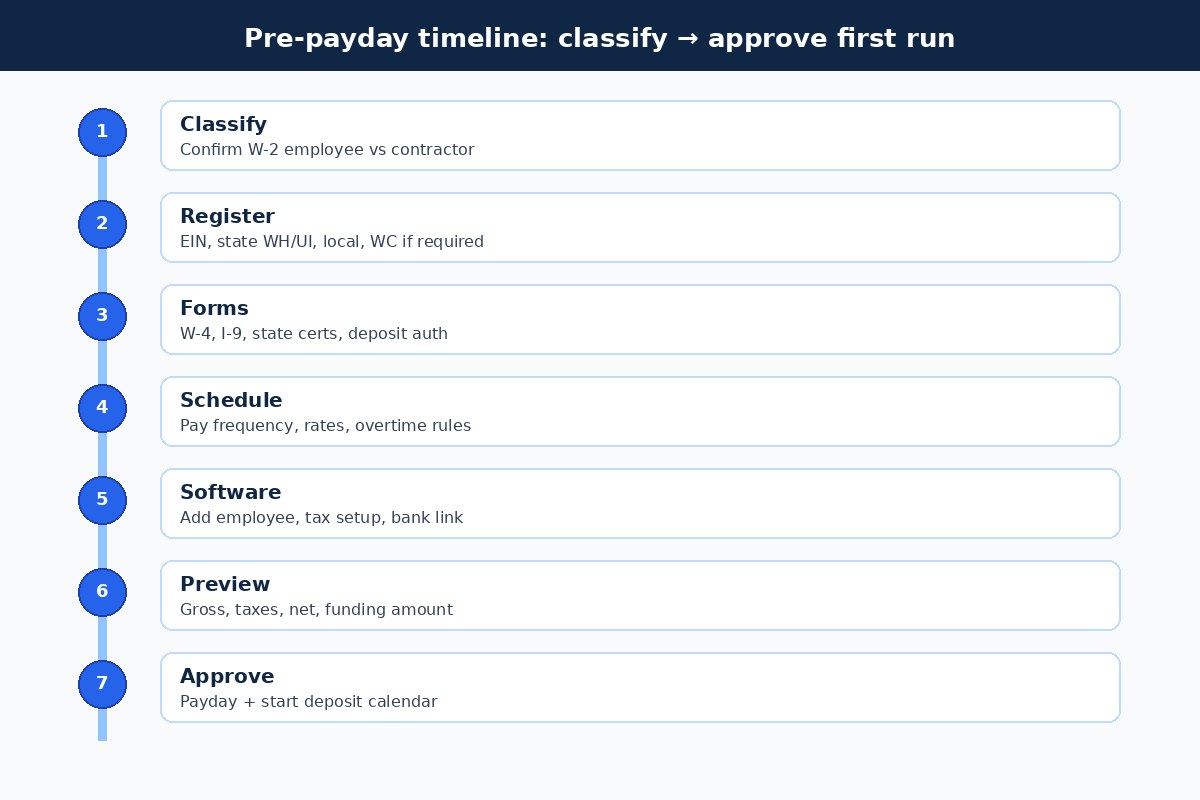
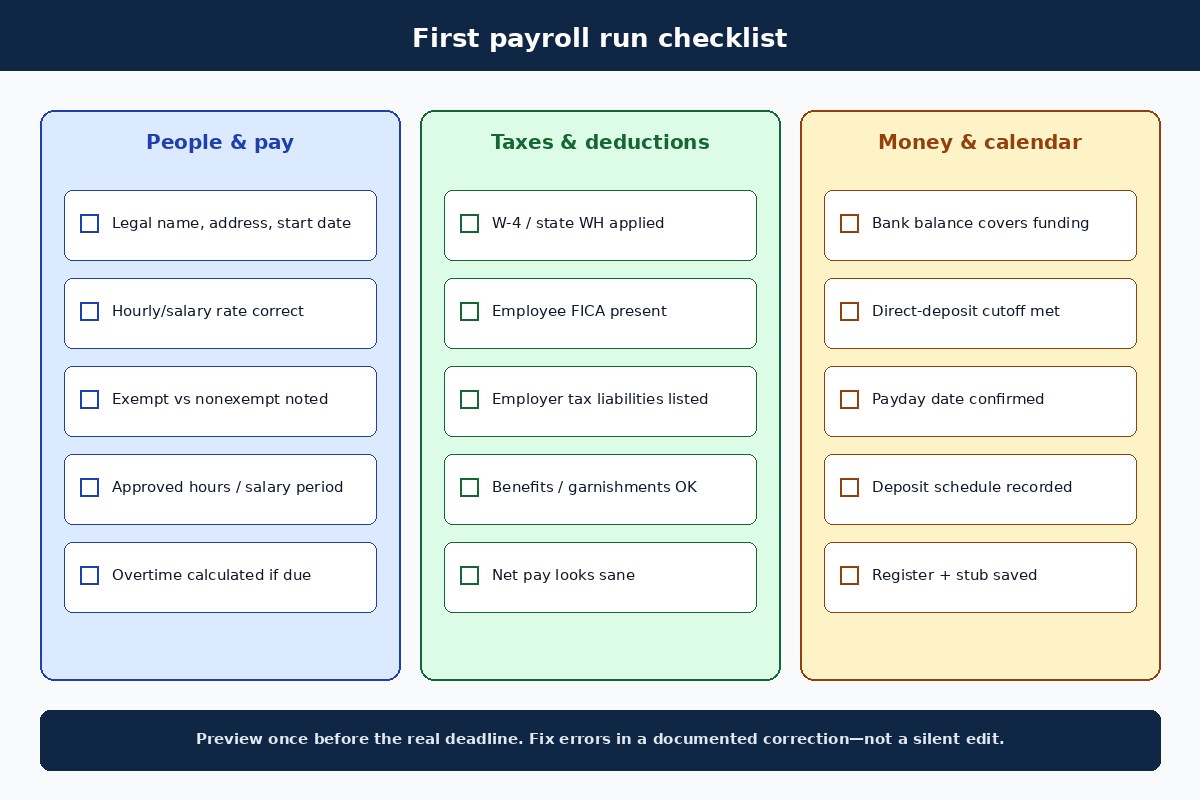
Each run starts with gross pay. For hourly workers, multiply approved hours by the rate, then add overtime and other taxable pay. For salaried workers, apply the agreed salary to the pay frequency and confirm exempt versus nonexempt status under wage rules. From gross, calculate required withholdings and authorized deductions: federal income tax, employee FICA, state or local income tax, retirement contributions, health premiums, garnishments, and similar items. IRS Publication 15 is the federal reference when a setting looks odd.
Before you approve, check hours or salary, overtime and leave, pay rate and classification, federal/state/local withholding, benefit deductions, net pay, bank funding, pay date, and deposit or filing deadlines that the run creates. Save the payroll register, time approval, paystub, tax-liability report, payment confirmation, and correction notes. If you find an error, document it and fix it through the provider or your accountant—do not silently rewrite a spreadsheet and hope agencies never notice.
Deposits versus filings after payday
Payroll has two clocks. The payday clock gets net wages to the employee. The tax clock deposits withheld and employer taxes, then files returns that report those amounts. Federal employment-tax deposits often follow a monthly or semiweekly schedule based on lookback liability; many new employers begin as monthly depositors in their first calendar year—confirm the rule in Publication 15 and any IRS notice. Deposits (often via EFTPS or your provider) are not the same as filing Form 941.
Form 941 generally reports wages, federal income tax withheld, and Social Security and Medicare taxes each quarter. Form 940 covers federal unemployment tax annually. State withholding and unemployment follow state calendars; local taxes may add more. At year-end you generally issue Form W-2 and submit wage data to the Social Security Administration. The detailed map of withhold versus employer share versus deposit versus filing lives in payroll taxes for your first employee—use that post for rates and calendars, and keep this runbook focused on the Ops sequence.
Ask your provider exactly what it remits, when it pulls cash, which states it supports, and what happens if your bank balance is short. You remain responsible for accurate inputs and enough lead time.
After the first payday
Confirm the employee received the correct net pay and can read the stub. Reconcile the payroll register to bank withdrawals. Mark deposit due dates on a shared calendar even when software claims to auto-file. File or confirm new-hire reporting if it was not completed at onboarding. Update your cash forecast for the next funding date plus upcoming tax deposits. Note any corrections while the details are fresh.
Set a boring routine: collect time by a fixed day, review the preview the same day, fund before the provider cutoff, and verify accepted deposits and filings after each cycle. The dates depend on your schedule; the habit matters more than the brand of software.
Common first-run mistakes
- Treating a supervised, ongoing role as a contractor to avoid payroll setup.
- Assuming entity formation registered you for state withholding and unemployment.
- Skipping I-9 timing or mixing I-9 files into casual cloud folders.
- Choosing a payday that ignores direct-deposit lead time and bank holidays.
- Approving the first live run without a prior preview of gross, taxes, net, and funding.
- Confusing tax deposits with Form 941 or state return due dates.
- Leaving new-hire reporting in an unread inbox until after the deadline.
- Underfunding the bank account the day the provider drafts payroll and taxes.
FAQ
How long does first-employee payroll setup usually take?
Plan days to a few weeks, depending on state account approvals, bank verification, and how quickly you collect W-4 and I-9 materials. Start registrations before the employee’s first week whenever you can.
Can I run payroll for one employee without software?
Yes, if you are willing to own calculations, deposits, filings, stubs, and W-2s. Many first hires still prefer software because deposit calendars and state rules are easy to miss when you are also running the business.
What should I preview before approving payday?
Gross wages, overtime, withholdings, employer tax liabilities, net pay, bank funding amount, pay date, and any deposit deadlines the run creates. Fix issues in the preview, not after cash has moved.
Are payroll tax deposits the same as filing Form 941?
No. Deposits move money on your deposit schedule. Form 941 reports wages and liability for the quarter. You need both calendars. Details are in the payroll-taxes companion guide linked above.
What if my employee works in another state?
You may need withholding, unemployment, or other accounts where the employee works (and sometimes where they live). Register before the first payday that creates those obligations, and confirm your software supports those jurisdictions.
Do I need workers’ compensation for one employee?
Many states require coverage once you have employees, with narrow exceptions. Check the work state’s insurance or labor agency before the start date.
Where does Gusto fit for a first hire?
Gusto is one payroll platform that helps small teams onboard employees, run payroll, support contractor payments on some plans, and handle common tax filings for supported locations. Compare current plans, fees, and state coverage on Gusto’s site before you enroll.
Related reading
- New hire payroll checklist for small businesses
- Payroll taxes for your first employee
- Do I need payroll for my LLC?
- W-2 vs 1099
- Gusto vs QuickBooks Payroll
- Best payroll software for 1 to 5 employees
- Payroll hub
Try Gusto for your first payroll run
If you want software that helps with employee setup, payroll calculations, direct deposit, and common federal and state filings for a small US team, Gusto is a practical place to compare. Gather your EIN, state accounts, employee forms, pay details, and intended schedule, then run a preview before you approve the first live payday.
Try Gusto (partner link). We may earn a commission at no extra cost to you. Confirm pricing, tax filing services, and state coverage on Gusto’s official pages before you enroll.
Again: this article is educational only. It is not tax or legal advice. Verify IRS Publication 15, state agency rules, Form I-9 instructions, and wage-and-hour requirements for your facts, and consult a qualified professional when classification, multi-state work, or deposit schedules are unclear.